Connecting to IRM 2
ICE provides several solutions that enable participants to obtain and calculate ICE Risk Model 2 (IRM 2) margins. These solutions are categorised into three areas, Margin Reports for Clearing Members, Margin Tools, and information to enable Margin Replication.
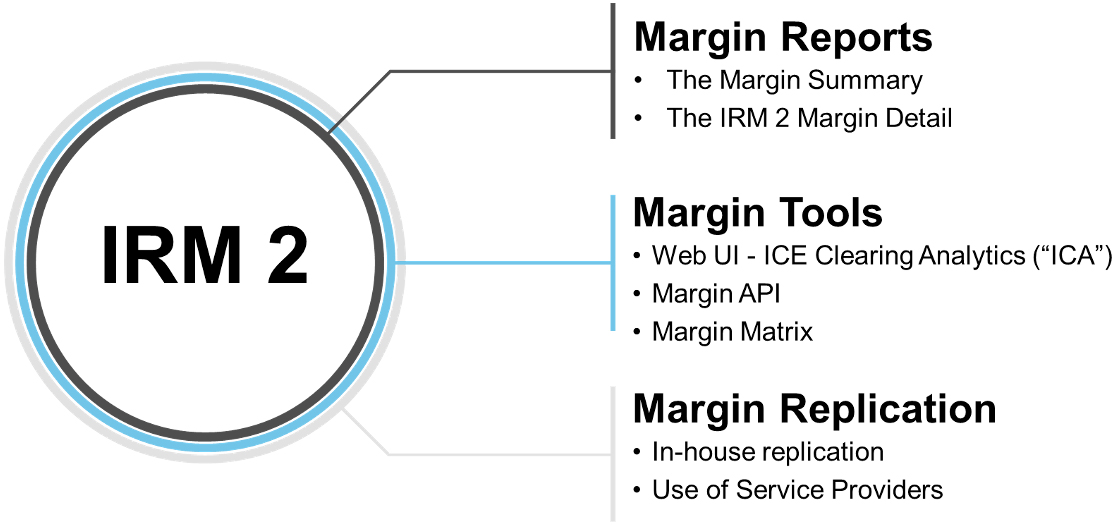
Margin Reports
Margin reports, containing a breakdown of the key IRM 2 margin components, are published during end of day clearing - see the Clearing Member Report Specification for details.
Margin Tools
ICE Clearing Analytics (ICA) allows users to upload portfolios, run interactive margin calculations and view detailed margin reports. ICE will provide a Margin API that can be used to run margin calculations for portfolios that are supplied in request messages. The Margin Matrix Lists margin rates for commonly trade outright and spread trades.
Margin Replication
Users who wish to replicate the margin calculation in-house can implement the model locally. Developer resources, including an External Developer Guide, Input Data File Specification and Reference implementation are available here.
A list of approved vendors who provide IRM 2 margin calculation services is available below. If you wish to use a vendor that is not on the list, please contact the vendor to ensure they are aware of the IRM 2 Project.
Margin Reports
Margin reports, containing a breakdown of the key IRM 2 margin components, are published during end of day clearing - see the Clearing Member Report Specification for details.
Margin Tools
ICE Clearing Analytics (ICA) allows users to upload portfolios, run interactive margin calculations and view detailed margin reports. ICE will provide a Margin API that can be used to run margin calculations for portfolios that are supplied in request messages. The Margin Matrix Lists margin rates for commonly trade outright and spread trades.
Margin Replication
Users who wish to replicate the margin calculation in-house can implement the model locally. Developer resources, including an External Developer Guide, Input Data File Specification and Reference implementation are available here.
A list of approved vendors who provide IRM 2 margin calculation services is available below. If you wish to use a vendor that is not on the list, please contact the vendor to ensure they are aware of the IRM 2 Project.
Connection options
See Approved Vendor list below for service provider solutions.
| Margin Solutions | Clearing Reports | Margin Tools | Margin Replication | |||
| Type | Clearing House Margin Reports | ICE Clearing Analytics - Web UI | Margin API | Margin Matrix | In-house Margin Replication | Service Provider |
|---|---|---|---|---|---|---|
| Supported Methodology | IRM 1 & IRM 2 | IRM 1 & IRM 2 | IRM 1 & IRM 2 | IRM 2 | IRM 2 | Check with Service Provider |
IRM 2 Approved Vendors
This list will be updated as more providers register with the IRM 2 vendor program.
| Vendor Name | Contact Details |
|---|---|
| 1Margin | |
| Adenza Inc. | |
| Alphalion Technology Limited | |
| ATPlatform | |
| Cassini Systems | |
| Cumulus9 | |
| FIS Global | |
| IF Informatica srl | |
| ION Group | |
| KRM22 | |
| Lynx | |
| Nasdaq Technology AB | |
| OpenGamma Limited | |
| Revendex Solutions GmbH | Peter Hollenstein T: +41 43 305 83 64 +41 79 677 94 99 |
| Sernova Financials Ltd | |
| TS Imagine |
Resources
Frequently Asked Questions
A list of questions and answers relating to ICE Risk Model 2.
ICE Clearing Analytics
ICE Clearing Analytics (ICA) is ICE’s new web-based platform for calculating ICE Risk Model 2 initial margin (IM) and related margin add-ons.
IRM 2 Methodology
ICE Risk Model 2 utilizes a Filtered Historical Simulation (FHS) Value-at-Risk (VaR) approach that models the behavior of a portfolio.
Frequently Asked Questions
A list of questions and answers relating to ICE Risk Model 2.
ICE Clearing Analytics
ICE Clearing Analytics (ICA) is ICE’s new web-based platform for calculating ICE Risk Model 2 initial margin (IM) and related margin add-ons.
IRM 2 Methodology
ICE Risk Model 2 utilizes a Filtered Historical Simulation (FHS) Value-at-Risk (VaR) approach that models the behavior of a portfolio.